Wednesday, September 2, 2026

Supporting kids & parents? 6 smart ways to protect your retirement corpus

 SOURCE:

 (a) https://economictimes.indiatimes.com/wealth/plan/supporting-kids-parents-6-smart-ways-to-protect-your-retirement-corpus/dont-forget-to-spend-on-what-matters/slideshow/133339471.cms


Supporting kids & parents? 6 smart ways to protect your retirement corpus

                           By 


                 Lavanya Mallidi                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                                         

How to balance retirement, children’s education and elderly parents
1/8

How to balance retirement, children’s education and elderly parents

Middle-aged people often have to juggle several major financial responsibilities at once -funding children’s higher education, supporting their ageing parents and building their own retirement corpus. Add EMIs, healthcare costs and other household expenses, and finances can feel really stretched. The key is to set clear priorities, safeguard non-negotiable goals and stagger other financial commitments rather than trying to fund everything at the same time.

ET Online
Retirement savings should remain a non-negotiable goal
2/8

Retirement savings should remain a non-negotiable goal

There is no loan for retirement, so your children should not become your retirement plan.
Continue at least the minimum baseline contribution towards retirement through instruments such as:
● Provident Fund
● National Pension System (NPS)
● Mutual fund SIPs
Pausing retirement investments for several years may make it difficult to recover the compounding that was lost.

Getty Images
Build an emergency fund and protect the family
3/8

Build an emergency fund and protect the family

Maintain an emergency fund covering around 6–12 months of household expenses. It should cover both:
● Income shocks, such as temporary job loss
● Expense shocks, including unexpected or uninsured costs
The family, including ageing parents, should have adequate health insurance with reasonable top-ups. If parents cannot get sufficient health insurance, a dedicated medical contingency fund may be necessary. A large term life insurance cover is also important

Getty Images
Children's education: Don't sacrifice retirement completely
4/8

Children's education: Don't sacrifice retirement completely

Parents naturally want to fund their children's higher education, but trying to pay 100% of the cost at the expense of retirement may not be sustainable. A more balanced approach could be to save a meaningful share of the education cost and use an education loan for the remaining requirement. At the same time, families can increase education savings by cutting unnecessary expenses or increasing income wherever possible.


Getty Images
5/8

Supporting elderly parents: Balance responsibility with practicality

Parents are a responsibility, but if they already have savings, investments, pensions or rental income, trying to fund everything yourself may not always be financially prudent. The priority should be ensuring that elders have:
● Adequate health insurance
● A dedicated medical contingency fund, where required
● Financial support for genuine needs

Getty Imges
Don't forget to spend on what matters
6/8

Sandwich generation finances: Sequence your goals

If your finances are tight, trying to save simultaneously for every goal could leave none of them adequately funded. A possible priority sequence is:
Emergency fund → Health insurance → Minimum retirement contributions → Essential parental support → Children's education funding. Lower-priority goals can receive more money once the higher-priority goals have reached their minimum required level.

Getty Images
7/8

The financial squeeze won't last forever

The sandwich-generation phase is not a permanent one. Children grow up, loans get repaid, and people can enter their peak earning years as they move towards their 50s. As cash flow improves, redirect money that was previously going towards college fees or loan repayments towards retirement savings. This can help accelerate retirement contributions during the later years of your working life.

Getty Images
8/8

Don't forget to spend on what matters

Managing multiple financial responsibilities can make every rupee feel like a problem to solve. But life cannot be only about meeting financial obligations.

Once essential goals are being funded, allow room for family trips, celebrations and meaningful experiences. Occasional, guilt-free spending on things that genuinely matter is not necessarily financial irresponsibility; it can make a long period of financial discipline more sustainable.

Getty Images

Tuesday, September 1, 2026

10 documents and details your family needs before it’s too late in events of sickness or death

(a) https://economictimes.indiatimes.com/wealth/plan/10-documents-and-details-your-family-needs-before-its-too-late-in-events-of-sickness-or-death/no-one-plans-to-get-sick-thats-exactly-why-you-should-plan-anyway/slideshow/133653573.cms


10 documents and details your family needs before it’s too late in events of sickness or death

            
Curated by Lavanya                       Mallidi Contributor
    

Aug 31, 2026, 06:14:07 PM IST


No one plans to get sick. That's exactly why you should plan anyway
1/10

No one plans to get sick. That's exactly why you should plan anyway

Nobody wakes up expecting a diagnosis, an accident, or a sudden decline. But when something like that happens, the families who cope best aren't the luckiest, they're the ones who already had their paperwork in order. Getting your affairs organized now, while you're healthy and thinking clearly, isn't about expecting the worst. It's about making sure the people you love aren't left guessing, searching, or fighting over what you would have wanted.

ET Online    
The 3 documents that decide who controls your money if you can't
2/10

The 3 documents that decide who controls your money if you can't

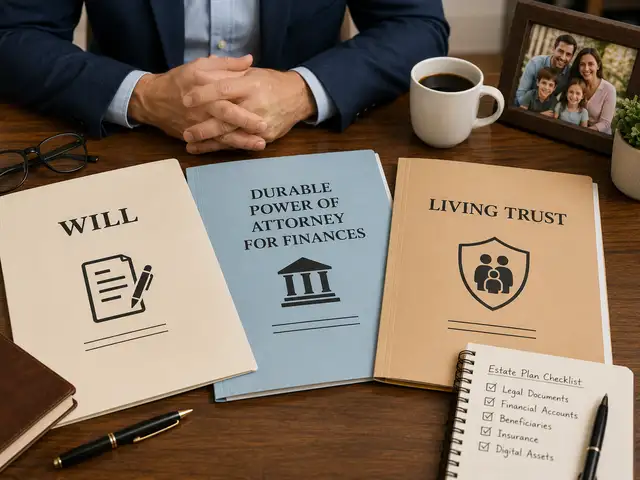
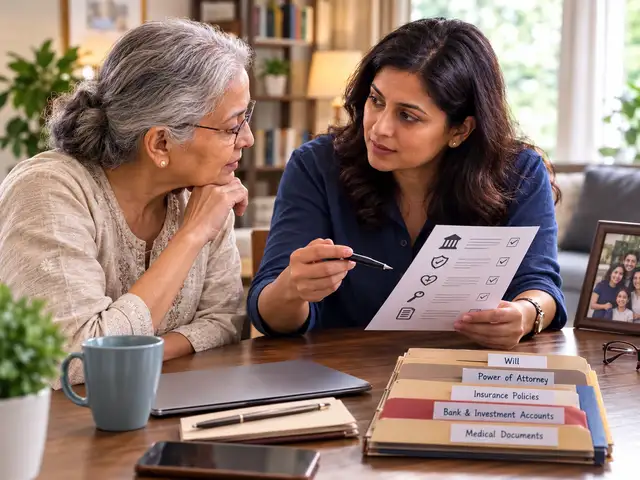
A will decides who gets your property, money, and belongings when you die, and if you skip it, your state's laws decide for you, not your family. A durable power of attorney for finances names someone to manage your money the moment you're unable to, whether that's temporary or permanent. A living trust goes a step further, naming a trustee to hold and distribute your assets on your behalf. Without these three pieces in place, even simple financial decisions can get stuck in legal limbo exactly when your family needs speed, not delays.

ET Online
What happens if you can't speak for yourself in an emergency?
3/10

What happens if you can't speak for yourself in an emergency?

This is where advance directives come in, legal documents that only activate if you can't communicate your own medical wishes. A Living Will spells out exactly which treatments you want and which you don't, so doctors and family aren't left guessing during a crisis. A durable power of attorney for healthcare names a proxy, someone who knows your values well enough to make the call for you. Together, these documents turn an impossible decision for your loved ones into something you've already decided for them.

ET Online
Choosing your healthcare proxy might be harder than writing a Will
4/10

Choosing your healthcare proxy might be harder than writing a Will

Your proxy isn't just a name on a form, it's the person who will stand in a hospital hallway and make life-altering decisions in your voice. The best choice isn't always your closest relative. It's whoever actually knows your values, stays calm under pressure, and will fight to honor your wishes even if other family members disagree. Naming a proxy is one of the few end-of-life decisions where getting the "who" right matters just as much as getting the paperwork right.

ET Online
One drawer, one folder, one safe: Where should everything actually live?
5/10

One drawer, one folder, one safe: Where should everything actually live?

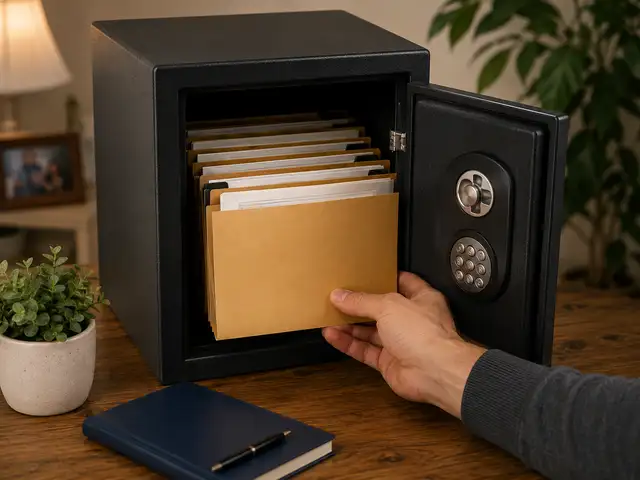
All the planning in the world doesn't help if nobody can find the documents when it matters. A simple file, a labeled drawer, or a notebook listing where everything is kept can work just fine, the key is consolidation, not complexity. A fireproof, waterproof safe adds extra protection for originals. And if anything sits in a bank safe deposit box, keep copies at home too, because those boxes aren't always instantly accessible in an emergency.

ET Online
Telling someone where your documents are matters more than writing them
6/10

Telling someone where your documents are matters more than writing them

A perfectly organized file does nothing if it's a secret. You don't need to share every personal detail, but at least one trusted person, a relative, a close friend, or a lawyer, should know exactly where to find your paperwork if something happens to you. This single step, often skipped, is the difference between a family that finds what they need in minutes and one that spends weeks searching drawers and calling banks.

ET Online
The personal information list that saves your family weeks of guesswork
7/10

The personal information list that saves your family weeks of guesswork

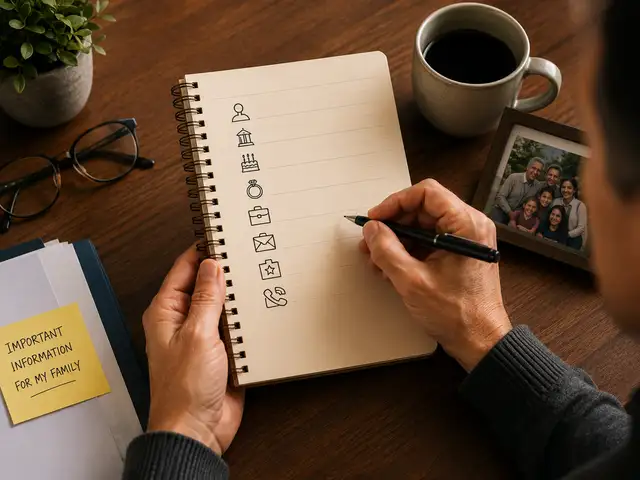
Beyond legal documents, there's a long list of practical details your family will need: your full legal name, Social Security number, birth and marriage certificates, employment history, and contacts for your doctors, lawyer, and financial advisor. It sounds tedious to compile, but every item on this list is something a grieving or overwhelmed family member would otherwise have to hunt down from scratch, often while also handling a funeral.

ET Online
Your bank accounts, debts and insurance policies need a paper trail too
8/10

Your bank accounts, debts and insurance policies need a paper trail too

Financial clarity is just as critical as legal paperwork: account numbers for every bank and investment account, insurance policies with agent contacts, a copy of your most recent tax return, and a clear list of debts and when they're due. Without this, loved ones can miss payments, lose track of assets, or simply not know an account exists at all. A single organized list turns a financial scavenger hunt into a straightforward handoff.

ET Online
A free conversation with your doctor could change how your story ends
9/10

A free conversation with your doctor could change how your story ends

Talking through advance care planning with your doctor isn't just wise, it's often free. Medicare covers this conversation during your annual wellness visit, and many private insurance plans do too. Your doctor can walk you through the medical decisions you're likely to face and help you understand what your choices would actually mean in practice. Then, sharing that conversation with your family removes the guesswork and prevents painful disagreements later.

ET Online
The plan you made last year might already be outdated
10/10

The plan you made last year might already be outdated

Getting your affairs in order isn't a one-time task you check off and forget. A divorce, a move, a new grandchild, or a major health change can all make an existing plan obsolete overnight. The people who stay truly prepared review their documents at least once a year and update them after any major life event. It takes far less effort to update a plan than to live with the consequences of an outdated one.


Tuesday, January 21, 2025

INDIA’S QUEST FOR AN INDIGENOUS NAVAL FIGHTER


Naval Fighters

 INDIA’S QUEST FOR AN INDIGENOUS                    NAVAL FIGHTER

                                  Cdr Sandeep Dhawan (Retd)

Mon, 20 Jan 2025 

The first Indian naval air station, INS Garuda, was commissioned in May 1953. However, it wasn’t until 1959 that naval aviation received its first fighter, the Hawker Sea Hawk. This was followed by the formation of INAS 300, the White Tigers, which consisted of 36 Sea Hawks. The Sea Hawks saw action during the Goa Liberation in 1961 and the Bangladesh Liberation in 1971, operating from India’s first aircraft carrier, INS Vikrant.

The Sea Hawks were decommissioned in 1983, and the Indian Navy had to wait five years before inducting the BAe Sea Harriers in 1988, which gained fame during the Falklands War. A total of 30 Sea Harriers were integrated into INAS 300. As the Sea Harriers neared the end of their operational life, the Indian Navy began receiving MiG-29K fighters in 2009, acquiring a total of 45 jets, including MiG-29KUB trainers. However, due to unsatisfactory performance with the MiG-29Ks, the Indian Navy has decided to procure 26 Rafale Marine jets and is expected to finalise these orders in the coming months.

The Quest for Indigenous Fighter

The Indian Navy faced resource constraints that hindered the development of an indigenous fighter jet, making it more practical to rely on imported deck-based fighters while receiving support from the Indian Air Force from shore. The Jamnagar-based No. 6 Jaguar Squadron and the Thanjavur-based No. 222 Su-30MKI Squadron are at the forefront of maritime operations.

Meanwhile, the Navy continued its pursuit of an indigenous fighter. In 1983, the Defence Research and Development Organisation (DRDO) initiated work on India’s second indigenous fighter program, the Light Combat Aircraft (LCA). The LCA prototype completed its first flight test in 2001 and received operational clearance in 2011. The Indian Navy became involved with the program early on. The NP-1 prototype was rolled out in 2010, and its first flight occurred in 2012. The NP-2 took to the skies in 2015.

The Indian Navy planned to acquire 50 deck-based aircraft for the aircraft carriers INS Vikramaditya and the under-construction Vikrant. Additionally, the Navy invested $22.4 million in six naval Tejas aircraft. Unfortunately, the underpowered Tejas did not meet the stringent requirements for a deck-based fighter, leading the Indian Navy to withdraw from the program.

Birth of a Twin-Engine Deck-Based Fighter

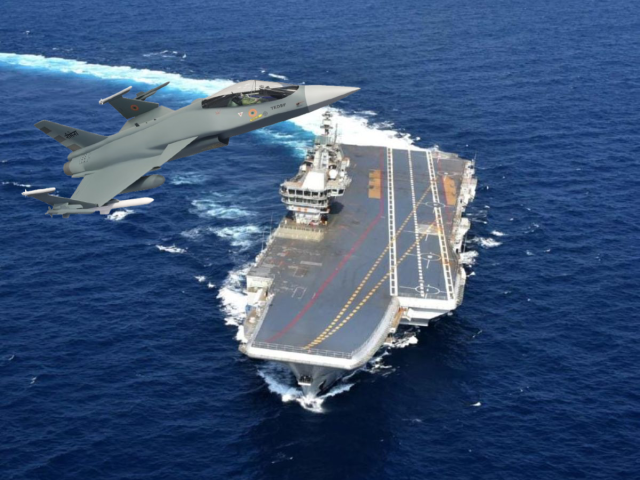
In response to the unsatisfactory performance of the Naval Tejas in 2020, the Indian Navy initiated the design of a dedicated naval fighter known as the Twin Engine Deck Based Fighter (TEDBF). The Aeronautical Development Agency (ADA), based in Bengaluru, has been entrusted with the design of this fighter.

While the project has received clearance from the Ministry of Defence (MoD), it still awaits critical approval from the Cabinet Committee on Security (CCS). The TEDBF is scheduled to undergo a Critical Design Review (CDR) by mid-2025. Upon successful completion of the CDR, the project will be presented to the CCS for funding approval. The ADA is seeking funding ranging from ₹13000 to ₹15000 crore for this initiative.

The ADA has classified the TEDBF as a 5-minus-generation fighter. It features a canard delta wing design, is semi-stealthy, and is built as a twin-engine fighter jet capable of achieving air superiority. Its intended roles include anti-ship operations, electronic warfare, and anti-access/area denial (A2/AD) missions, as well as support missions. The advancements in the Indian Air Force’s Advanced Medium Combat Aircraft (AMCA) program have also helped the TEDBF programme in many ways.

The TEDBF features advanced stealth capabilities essential for operational effectiveness in hostile environments. Its design includes radar-absorbent materials and blended surfaces to reduce radar cross-section (RCS). Twin engines minimize infrared (IR) emissions, enhancing protection against detection by heat-seeking missiles.

A key innovation is the diverterless supersonic inlet (DSI), which automatically adjusts for optimal engine performance, increasing thrust and fuel efficiency, especially at high speeds. Innovative serpentine air intakes improve stealth by concealing engine fan blades and optimising airflow, contributing to lower RCS. These intakes also enhance performance across varying altitudes and speeds.

Additionally, the TEDBF is equipped with advanced electronic warfare (EW) systems that jam and deceive enemy radar and communication, enhancing survivability in contested environments. Overall, the TEDBF showcases cutting-edge aerospace technology, positioning the Indian Navy at the forefront of modern naval aviation.

Commercial Viability

When evaluating the feasibility of a fighter jet programme, three key terms should be considered: Program Unit Cost (PUC), Unit Procurement Cost (UPC), and Operational Cost. PUC is calculated by dividing the total program cost by the total number of aircraft produced. In contrast, UPC is determined by dividing the cost of the most recent production contract by the number of aircraft included in that contract, which typically excludes most research and development (R&D) and support costs.

A comparison of various fighter jet programs:

Aircraft TypeUPC (Million USD)PUC (Million USD)Program Cost/Units
F/A-1878.4 (2007)95.3 (2005)44.03 Bn, 462
Rafale-M67.8 (2005)145.7 (2005)8.72 Bn, 60
AMCA80-100 (estimated)60 (estimated)~6 Bn, 125-200
LCA Tejas Mk1 & 1A40, 7930, 231.2 (40)1.9 Bn (180)
Tejas Mk2NANA1.2 Bn, 120-250
TEDBFNANAExpected 2 Bn, 100

In the long run, the cost per flight hour can significantly impact the viability of a programme. The estimated cost per flight hour for the F/A-18 Super Hornet ranges from $10,000 to $24,000. This range is influenced by factors such as mission complexity, maintenance requirements, fuel consumption, spare parts, and support infrastructure. In comparison, the cost for the Rafale-M is estimated to be between $16,500 and $19,000 per hour. The cost per flight hour for the F-35, however, is considerably higher, ranging from $38,000 to $50,000 depending on the aircraft variant. Currently, there is no data available regarding the cost per flight hour for the TEDBF or AMCA.

Getting back to the advantages of local production, we can consider the example of the indigenous production of the Su-30MKI. Many people compare the Su-30MKI produced in India by Hindustan Aeronautics Limited (HAL) with those produced in Russia. While the Su-30MKI in India may have higher initial costs, it provides long-term benefits such as self-reliance, local job creation, and potential export opportunities. On the other hand, acquiring the Su-30 directly from Russia may seem more cost-effective initially, but it does not offer the same strategic and economic advantages as domestic production.

When examining the production and operation patterns of various fighter programmes, several facts emerge. Firstly, aircraft designed by a single country are not necessarily more expensive than those developed through international cooperation. Additionally, single-nation development does not guarantee lower costs, as evidenced by the fact that U.S. fighters like the F-35 and F-22 are significantly more expensive than European fighters such as the Rafale-M and Gripen. Furthermore, long production runs do not always result in less expensive aircraft. Thus, maintaining continuity in development is the best way to avoid cost overruns. Finally, development costs are influenced more by the management and development history than by the aircraft’s actual capabilities.

The Challenges

India faces a significant challenge in achieving self-reliance in defense manufacturing, particularly in developing advanced aero engines, which are crucial for the performance and reliability of fighter aircraft. The Kaveri engine, developed by the Gas Turbine Research Establishment (GTRE) since the 1980s for the LCA, has encountered numerous technical issues and has not met performance standards, leading the Tejas to depend on an American-supplied GE engine.

To address this, the DRDO has sought partnerships with international firms like France’s Safran and the U.S. General Electric to expedite indigenous engine development. However, India has already faced two years delays with the GE F404-IN20 engine for the Tejas Mk1, anticipating similar issues for the Tejas Mk2 and AMCA programmes.

The Way Forward
The TEDBF, which focuses on indigenous development, aims to provide cost-effective solutions while integrating advanced technologies from the AMCA program. While the Indian Navy has supported the Tejas program, it is now time for the Indian Air Force to reciprocate by backing the TEDBF program, particularly through its involvement in the Omni-Roll Combat Aircraft (ORCA) programme, a land-based variant of the TEDBF.

However, it is unlikely that the IAF will support the ORCA program. Nonetheless, this does not diminish the importance of naval aviation in supporting India’s rise. According to estimates from the Centre for Economics and Business Research in London, China is projected to be the world’s largest economy for 21 years by 2036, with the United States expected to reclaim its position by 2057. Ultimately, India is anticipated to surpass the US around 2081.

To achieve these economic goals and maintain its global status, India will require a strong navy with worldwide reach. This ambition can only be realised if the momentum of the ‘Atmanirbhar Bharat’ initiative is sustained. The TEDBF is one such initiative that could revitalise naval aviation and help India achieve greater heights.

Cdr Sandeep Dhawan (Retd)

Author
A veteran of the Indian Navy, Cdr Dhawan served in the Navy from 1988 to 2009. He was a Maritime Reconnaissance Pilot and a Flying Instructor. He is a geopolitical analyst and writes for various online websites and organizations.